digest

Short Summary
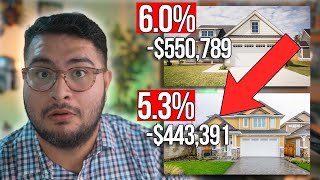
Main recommendation: Whether to prepay a mortgage or invest instead depends on your age, interest rate, and discipline, but the video's case study favors investing early when your mortgage rate is low and your expected returns are high. Using a $500,000, 30-year mortgage at 5.3%, the "Manny the Mutant" investing approach outperforms "Debt-Free Dave" by about $800,000 over 30 years, while Dave's prepayment strategy is presented as a better fit for people who need the discipline of eliminating debt.
Key Points
- In the case study, both borrowers have a $500,000, 30-year fixed mortgage at 5.3% with a $2,768 monthly principal and interest payment.
- Debt-Free Dave pays an extra $1,000 monthly, becomes mortgage-free at about 16.5 years, then invests the full $3,768 monthly for the remaining 13.5 years, ending with about a $1 million portfolio.
- Manny the Mutant invests the extra $1,000 monthly from the start, assuming about a 9% long-term return, and ends with about $1.8 million.
- The speaker says the 5.3% rate was chosen conservatively; many people who locked in rates well under 4% a few years earlier would see an even larger gap favoring investing, potentially a million-dollar difference.
- The video states that most Americans lack the discipline to invest instead of paying off debt, so prepayment is likely to work well for them, while 'financial mutants' who know their own behavior and the value of their money may benefit more from investing.
- For borrowers over 45 who have already built wealth, the speaker says the wealth multiplier is lower, so de-risking and potentially prepaying debt becomes more reasonable.
Details Worth Noting
- Concrete instructions: Compare your mortgage interest rate with your realistic expected investment return; the video's example uses a 5.3% mortgage rate versus about a 9% assumed long-term return for a 30-year-old investor.
- Concrete instructions: Before prepaying a mortgage, the speaker says to save and invest at least 20 to 25% of income toward retirement goals; he frames prepayment as a later step in the financial order of operations, not a first priority.
- Concrete instructions: Under age 45, the speaker advises building wealth first and not prepaying the mortgage until you are paying over the required amount and building your investments.
- The speaker used 5.3% as a more generous (conservative) assumption than the sub-4% rates many borrowers had locked in three to four years earlier, and notes that mortgage rates today are higher than 5.3% if you walked in off the street.
- The speaker, who is over 45, paid off a mortgage with a remaining balance of $43,161.50 that had been about $90,000 a year earlier during his book tour, after previously making extra payments and keeping cash earning close to 5%.
- He notes that he still carries commercial real estate debt, which he views as a tool, and that a bank offering commercial mortgages below 3% makes borrowing attractive.
- An insurance claim check made out jointly to the mortgage company was another reason he chose to pay off the mortgage, since getting the lender to sign off took three or four weeks.
Bottom Line
The mortgage decision depends on the interest rate, your age, and whether you have the discipline to invest consistently; for young borrowers with rates above 5 percent, the video's numbers suggest investing can produce a far larger long-term result than prepayment.