digest
Short Summary
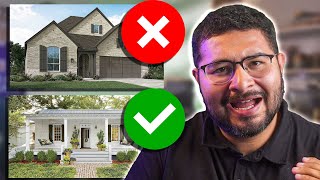
Main recommendation: Buy a boring, well-presented first home rather than a bargain that needs major work, keep your payment to no more than 25% of take-home pay, and get title insurance, a survey where applicable, and a home inspection. The speaker also cautions against ugly houses, poor floor plans, and corner lots that can look appealing but resell for less.
Key Points
- The 25% rule: keep the total payment, including taxes and insurance, to no more than 25% of take-home pay on a conventional loan.
- A 20% down payment lets you avoid PMI (private mortgage insurance), an additional monthly cost.
- Ugly houses are hard to fix and tend to sell cheaply later because buyers avoid them, so a low price usually reflects a real problem.
- Poor floor plans, such as a bedroom you can only reach through another bedroom, are a warning sign, as are homes built by piecemeal additions with no original plan.
- Corner lots often look good from the street but may have a small, pinched backyard, which can lower resale value.
Details Worth Noting
- Concrete instructions:
- Calculate your total monthly housing cost (mortgage, taxes, insurance) and confirm it is no more than 25% of your take-home pay.
- Use a 15-year fixed-rate loan when possible, as the speaker mentions this alongside the 25% guideline.
- Always get title insurance whenever you buy real estate.
- Get a survey for any property that is not a standard, pre-platted subdivision lot, such as acreage, where the stated size may be wrong (the speaker's example: three acres turning out to be 1.75).
- Always get a home inspection, even if you are handy, because a professional will check things a first-time buyer may miss.
- Choose a modest, "boring" house with a conventional layout, and avoid properties that require a full rehab, tearing out structures, or adding on. Cosmetic updates like carpet, outdated fixtures, or gutters are considered manageable.
- Check how a corner lot's backyard is laid out before buying, and ask whether a future buyer would have the same concern.
- The speaker has bought and sold several thousand pieces of real estate and says he still gets an inspection on every purchase.
- The speaker says the 25% guideline and 15-year fixed rate apply to a conventional loan scenario; these are the speaker's views and not professional financial advice.
Bottom Line
A first home should be chosen for resale appeal and low risk rather than an excitingly low price, so favor a plain, well-laid-out house and verify its condition with inspection, title, and survey work before committing.