 digest
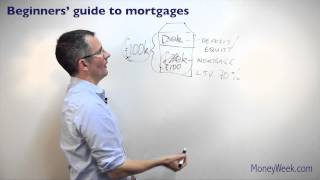
one of the most important financial decisions you'll ever take is getting a mortgage it's one of the biggest Financial commitments most people make alongside private school fees for their children if they're lucky enough to be able to afford them so what is a mortgage that's what we'll cover in this video and what do some of the key bits of jargon plastered all over the newspapers actually mean right a mortgage is a secured loan that makes it different from a loan that you might take out for example unsecured to buy a car or just simply by racking up credit card debt or using a store card those are unsecured all right now the difference is very simple a secured loan a mortgage here's the deal you go to a bank say I want to borrow £100,000 for argument sake the bank says that's fine Tim but we want the loans secured on an asset that asset being the house you plan to buy the deal is simple and it's a two-sided deal in return for that security the bank will offer you a low interest rate much lower than all say a car loan or a credit card or a store card loan right you can pick up mortgage rates for around 4% four 5% at the moment depending on the period you go for whereas unsecured Store card loans could cost you up to 30 all right so that's the upside the interest rate is low but that's because the loan is secured and that means if you fail to repay it or keep up with repayments the Bank Reserves the right to seize your property and sell it and use the proceeds to repay the loan right so a mortgage has one benefit upfront the interest rate tends to be a lot lower you can get on other loans and that's because the bank has a lot of security in the form of your property all right now property prices can go down as well as up all right which is why Banks don't always lend or certainly not anymore the full value of the property to somebody who wants a mortgage okay the hey days the ridiculous days before the financial crisis are now long gone so that brings me on to my first piece of jargon related to mortgages loan to value LTV now if you see that what does that mean and what practical consequence does it have for you trying to get a mortgage well here's how it works uh people who seen my videos before we know that Graphics are a particular Forte of mine so there's a house all right and let's say that the value of the house on the open market is 00,000 all right and you plan to put down a £3,000 deposit lucky you and that means you need a £70,000 loan or mortgage all right now how do I know You' put down a 30,000 pound deposit well maybe you can't afford a 30 ,000 deposit the deposit is down to what you can manage to scrimp and save together okay persuade parents or friends to give you whatever happens to be so you've got deposit from somewhere all right and the rest is the mortgage so a combination of what's called Equity that's your bit and a loan from the bank secured on the property makes up the funding for the £100,000 property all right now here the LTV as you'll sometimes see it quotes in the Press bit of jargon there the loan to value ratio is simply that compared to that as a percentage all right so here the LTV 70,000 as a proportion of the value of the property literally the loan to value ratio is 70% all right and in simple terms basically the higher that is the harder it is to get the loan all right now back in the ridiculous days pre financial crisis there were banks around that would say no problem you could have uh ltvs of more than 100% 125% you could actually borrow more than the value of the property from a bank they even give you hints and tips as to what to do with the extra right so on a £100,000 property this might sound a little mad but it was happening you could borrow £125,000 and I'm not kidding the bank's website say saying things like well book yourself a holiday buy a car with the extra now that is madness and got a lot of people into big trouble which is why ltvs tend to be a lot lower now okay um because of something called negative equity which is the third bit of jargon I'll cover just now but here's my takeaway okay the higher the loan to value ratio naturally um the higher the interest rate and the harder the mortgage will be to come across so if you can scrip together as much of a deposit as you get a hold of bring down the loan to value ratio but tend to find that better deals then become available why are we no longer seeing loans in excess of 100% of the value of the property well unfortunately if you allow someone to borrow a huge amount of money and the value of the property then drops so imagine for example if I take out the deposit all together all right and I make the loan 100 % all right so imagine that the whole thing still following my scribblings here is funded by a mortgage the danger is this if the value of the property then drops which it could do to 90,000 you are now in something called negative equity it's the danger taking out loans that are a high proportion of the value of the property negative equp means the property is not enough to pay back the loan 90,000 if you sold the property tomorrow won't pay back a loan of £100,000 that's a problem okay it can leave you unable to move for example so that's a trap that quite a few people unfortunately knowingly other or otherwise probably unknowingly H into it's probably PR decided to come off okay once we hit the financial crisis in 2007 and that's why unfortunately banks are now being very very conservative unfortunately because it makes it harder for a lot of people to get onto the property ladder at all okay so that's that's negative equity what the Americans call being underwater okay now once you've decided how much you're going to borrow 70,000 in my previous example you've got a couple of choices you can either go interest only or you can go repayment style mortgage okay what does that mean basic Choice all mortgage products all loans fall into one of those two camps essentially no matter how they're written up in the advertising literature they're either interest only or repayment that's worth bearing in mind interest only is tempting with interest only you borrow let's say £100,000 and you commit to just pay the bank the interest on the loan okay at whatever rate that happens to be 4% for argument sake so the 100,000,000 you're not paying back all right now how's that how's that work you've got to pay it back at some point the idea is you just write a check if you like you pay the bank the interest every month on the loan and then you set up another vehicle that will eventually pay off the capital because you got to still pay off the £100,000 as well as the interest all right and that could be some sort of equity based product all right they used to be known as endowment mortgages now upside to interest only loans the payment every month to the bank is lower than it would be if you were paying them back interest and some of the original capital of £100,000 okay that's the upside the downside is you'll be pretty damn sure that whatever you're going to use to repay the capital after 20 or 25 years for argument sake is enough to do the job and the problem a lot of people found or have found in the past is they set up these kind of little investment funds on the side saying well after 20 years this will have grown foot 100 fund to £100,000 or more so I'll be able to clear my mortgage and have a party all right problem is if the equity Market plummets your little savings vehicle isn't enough to repay the original loan then you got a problem okay so interest only mortgages attractive because the initial payment to the bank will be relatively low but you've got to have some way to pay off the uh Capital that you've borrowed in the future the alternative is a repayment mortgage as the name suggests there every month your repayment to the bank is interest on the loan 4% for argument say plus a little bit of the original capital you borrowed so the idea being that after 25 years for example you will have cleared all of the 00,000 if that's the amount you borrowed that you owe the bank okay now downside to that one is you will find your monthly payments to the bank are a little bit higher because they include interest and some capital of course the upside is you know provided you keep your job and keep up the repayments you will clear your mortgage after 20 or 25 years right no doubt about it because you are chipping away at the capital every month okay now that means that normally I would recommend if you can afford it you do a repayment mortgage of some sort but watch out okay there are a couple of traps which I want to finish this video on this is a beginner's introductory guide there are a few traps to watch out for with mortgages so decision tree so far is um how much do I want to borrow how much do I need to borrow how much of a deposit have I got versus the amount required to buy the property I'm after okay uh that will affect the deal you can get from a bank but then you need to decide on the amount you're borrowing am I going to go down the interest only or the repayment style route okay and I've already highlighted a couple of criteria to think about and making that decision now let's say for a moment I've picked a repayment style mortgage there are one or two other things to look out for number one when you're looking up mortgage rates again you can look up on sites like money fax and money supermarket and so on um you can you can look up the these rates on a number of different sites when you're looking at mortgage rates just watch out because you might see a juicy low rate aha brilliant you know for argum three% and you think well that's a really low interest rate I'm having some of that watch out number one is there an arrangement fee on top some borrowers sorry some lenders will charge you quite a meter Arrangement fee we could be talking you know ,000 ,00 two grand just to set up the mortgage right all of a sudden that 3% is not looking quite so good so you need to compare apples with pairs you know is 3% with an arrangement fee the same as 5% with no Arrangement fee for argument sake all right so there's one little trap watch out always check the arrangement Fee number two watch out for lowball initial deals the ones where the bank says oh come to us borrow from us borrow from us because what we can do is set you up for a few years on a really low rate then watch out because once that low rate period ends you might be kicked into What's called the standard variable rate svr and that may be first of all not a fixed rate and secondly a lot higher all right thirdly Redemption penalties if you take out a deal and it commits you to a minimum number of repayments over a number a number of years watch out you're not stung okay if you need to sort of switch product or kick out of there early okay you know in other words something goes wrong you may be stung for a big Redemption penalty simply to get out of the mortgage early or move it or change it okay um so there's uh a few traps to watch out for when you're shopping around for a mortgage all right so just to recap there a mortgage is a secured loan good news is that means you can borrow lower than you would on other types of loan okay first decision to make how much do I need to borrow the less you need to borrow the better the deal you'll get okay um third thing just to bear in mind is that um you got to make a decision between interest only and repayment okay and you've also got to make a decision between paying a fixed rate and paying a variable rate of interest lots of things to think about here fixed rates certainty variable rates well the opportunity maybe if you're on mortgage payments to go down if interest rates fall as well is up if they rise okay so they have another decision to make there and do watch out for the little things in the tail including Arrangement fees low initial rates to grab you in and Redemption penalties to download this free video to your favorite mobile device find us on iTunes by searching for money week and the entire video archive is also available free just visit money we.com
transcript
MoneyWeek - Beginners' guide to mortgages - MoneyWeek investment tutorials
Community upload. AI output has not been independently verified.